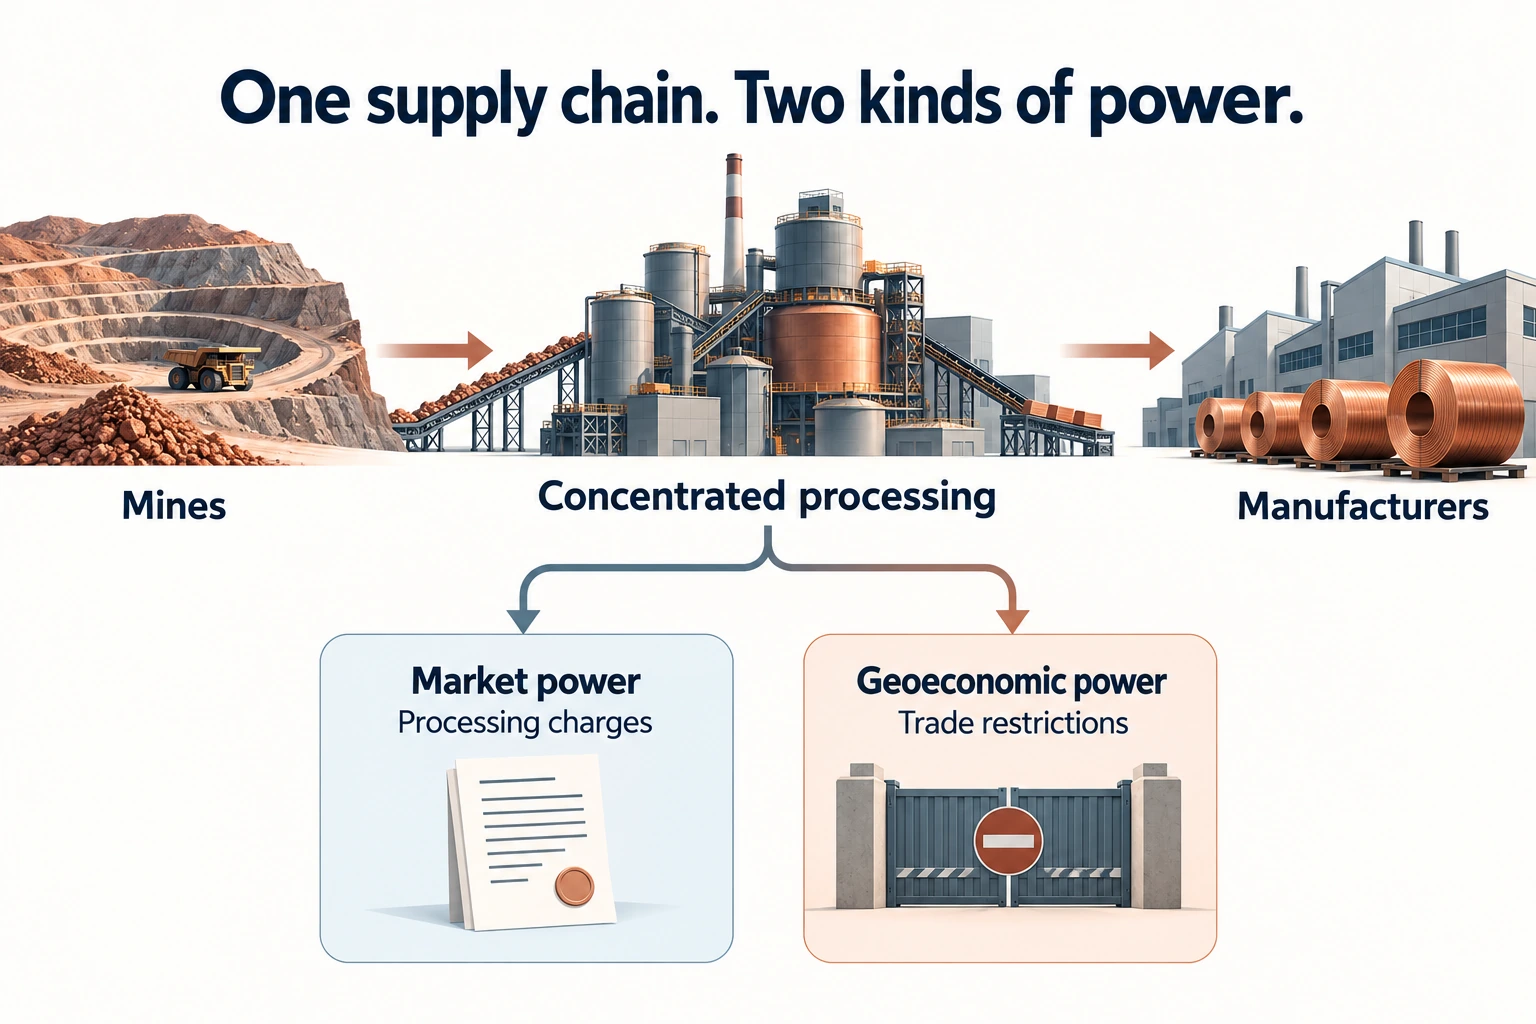
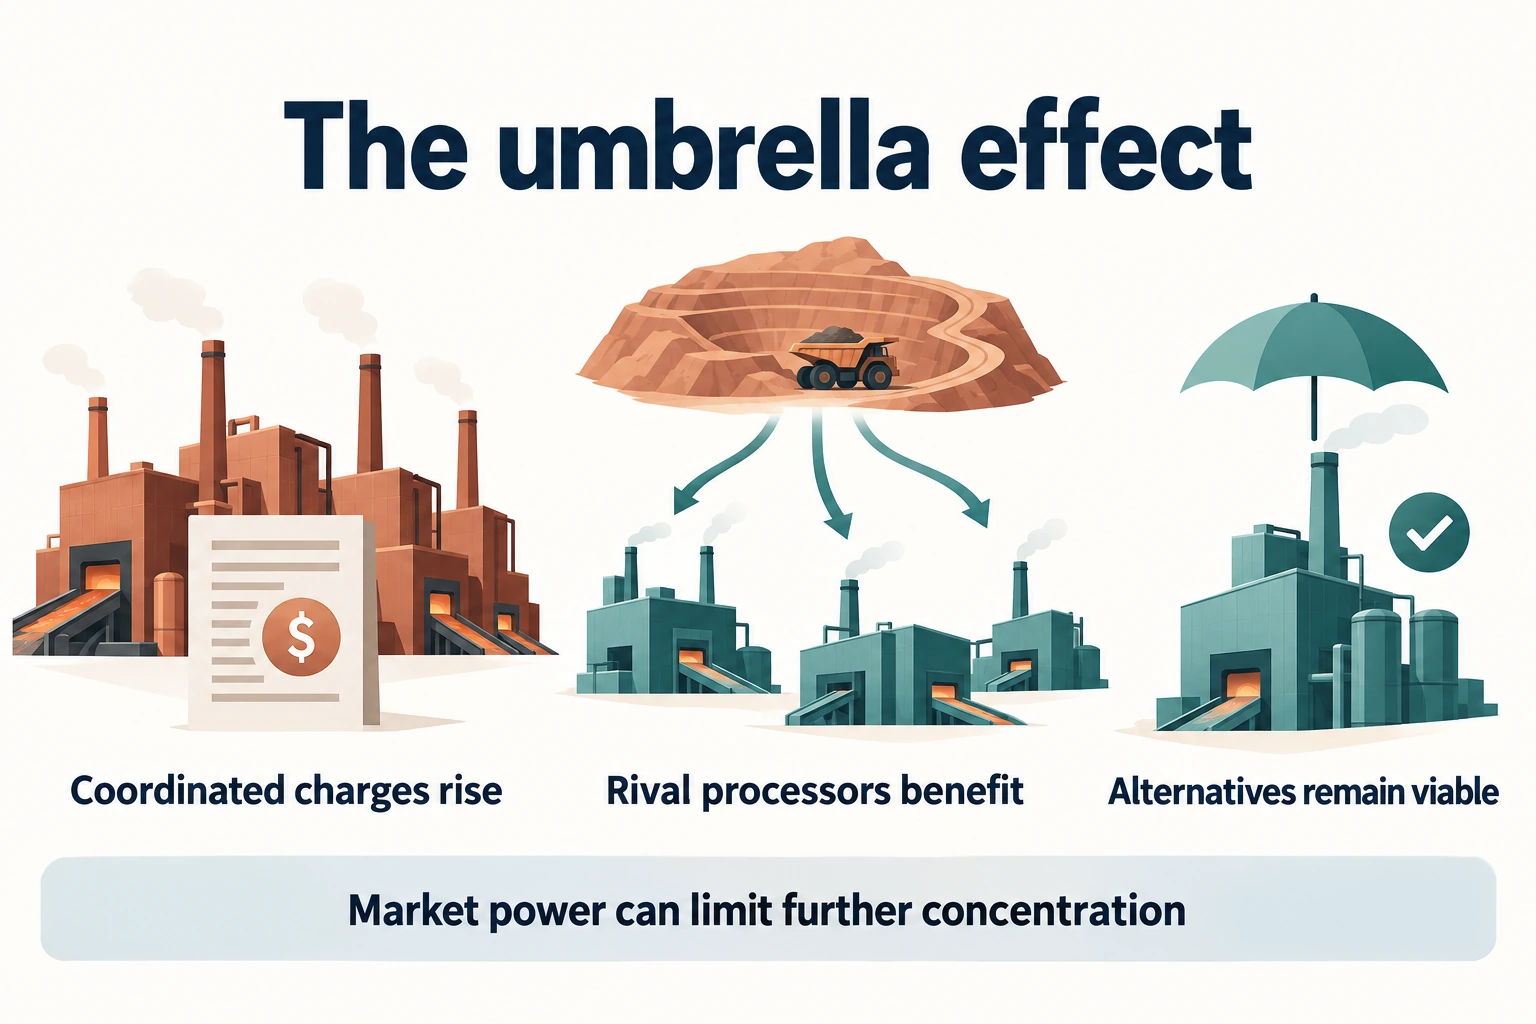
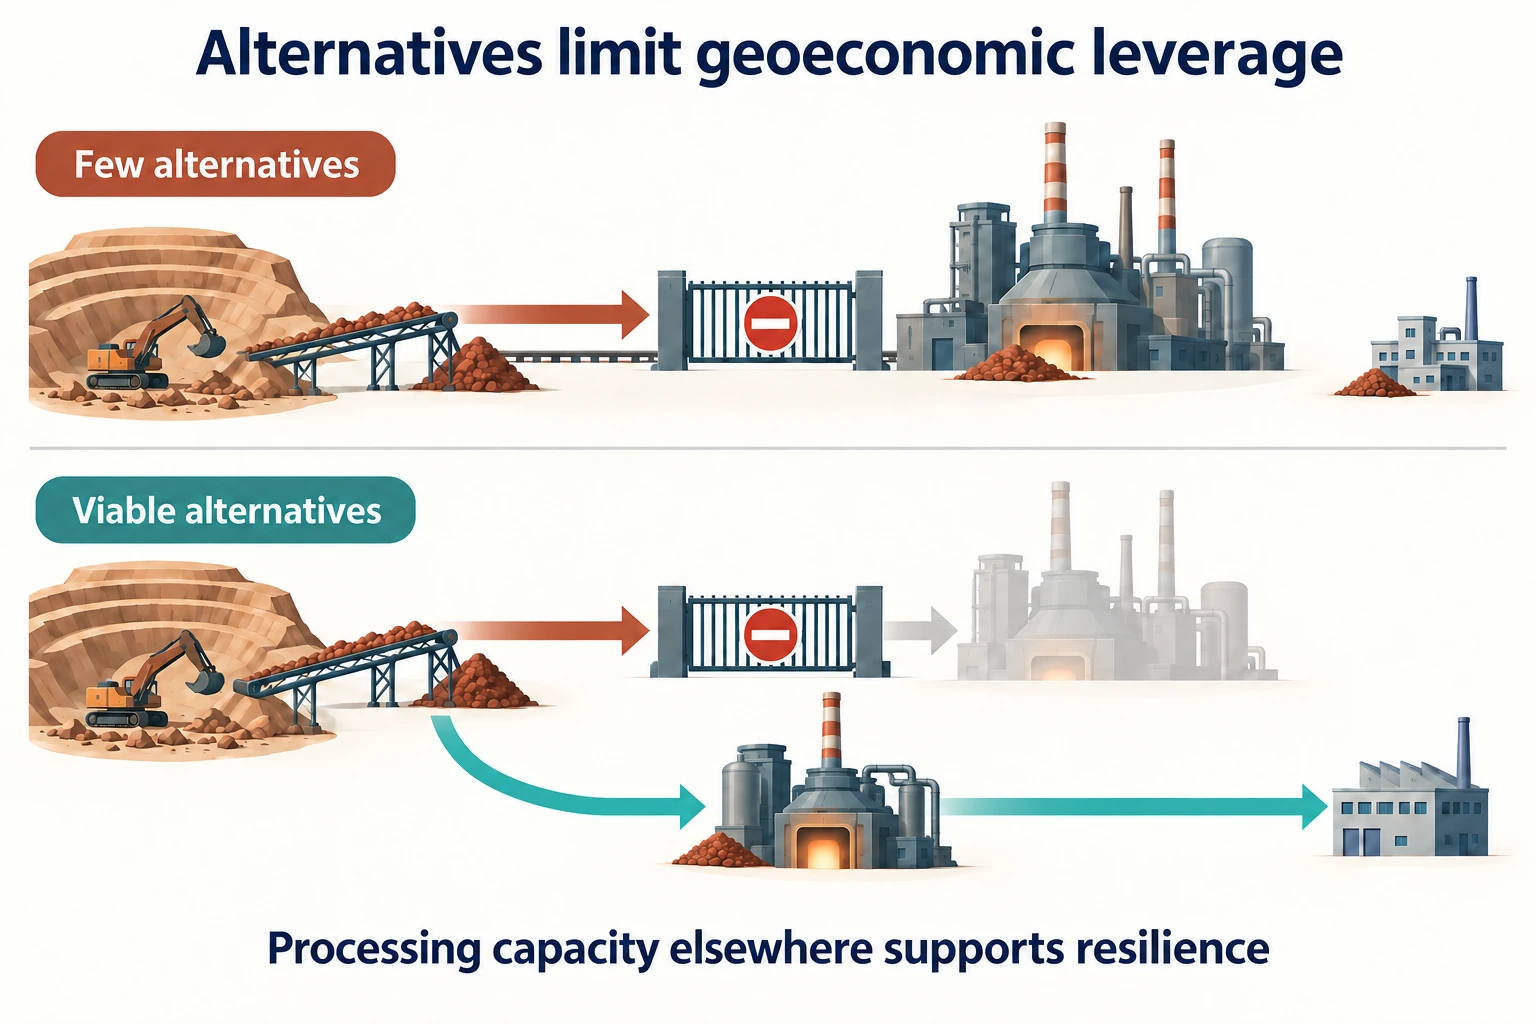
China has become the dominant player in the midstream processing of many critical minerals. This concentration has enabled it to wield geoeconomic power through trade restrictions. We show, however, that concentration can also create an opposing force: market power exercised through national industry coordination. When a country's processors coordinate to raise processing charges, higher charges divert supply to processors elsewhere and increase the charges earned by those competitors. This “umbrella effect” can slow further consolidation, reducing the country's geoeconomic leverage. We quantify this tension in the copper supply chain—an essential input to the energy transition—where the China Smelters Purchase Team coordinates processing charges. We develop a framework for critical-mineral supply chains with coordinated midstream firms. Our results show that, absent coordination, the supply chain would be substantially more concentrated and less resilient to a range of geoeconomic shocks.
Concentration in mineral processing creates both market power over processing charges and geoeconomic leverage through trade restrictions.Coordinated processing charges can divert supply to rival processors and raise their earnings, preserving alternatives outside the coordinating country.Preserving alternative processing capacity can limit dependence on a dominant country and improve resilience to trade restrictions.
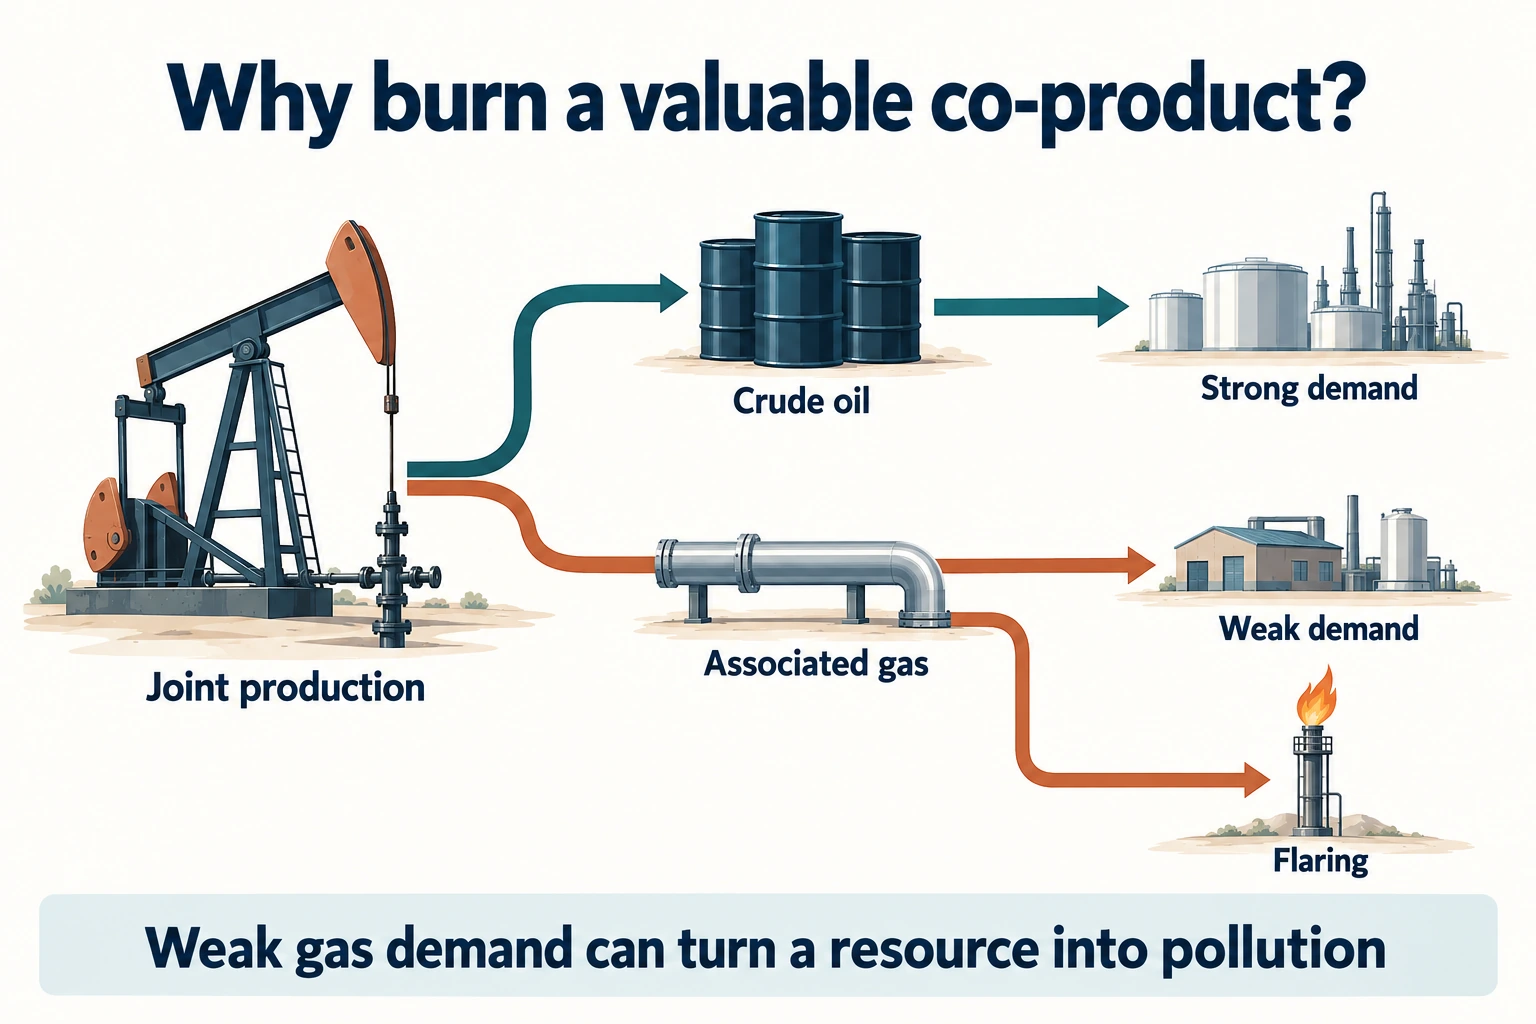
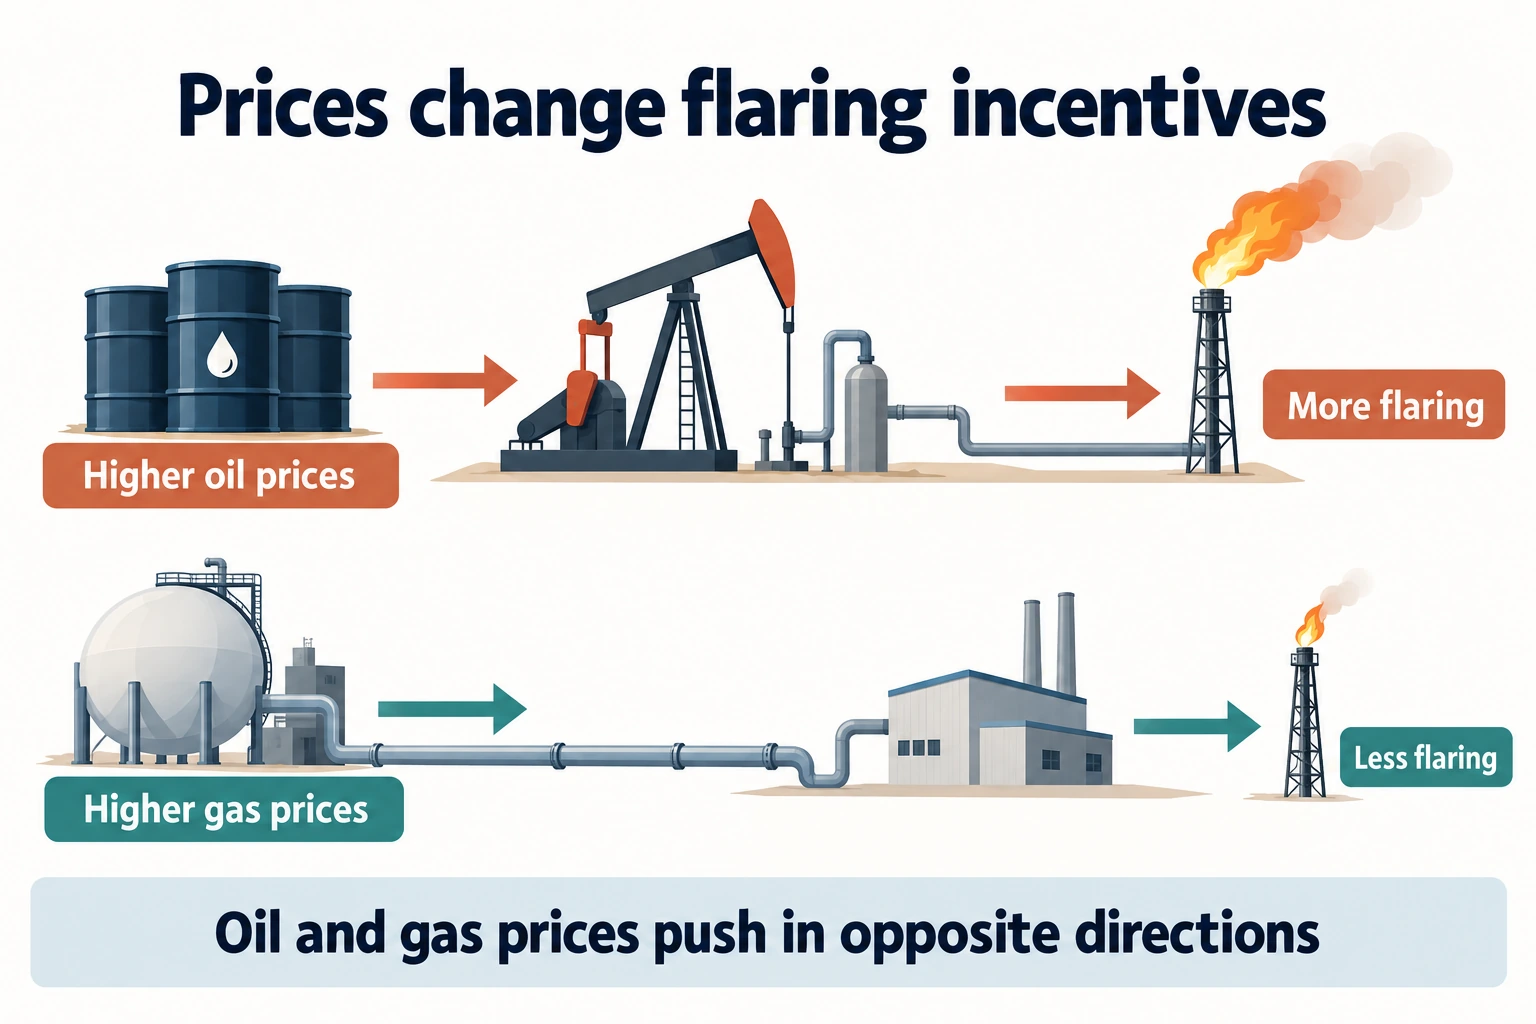
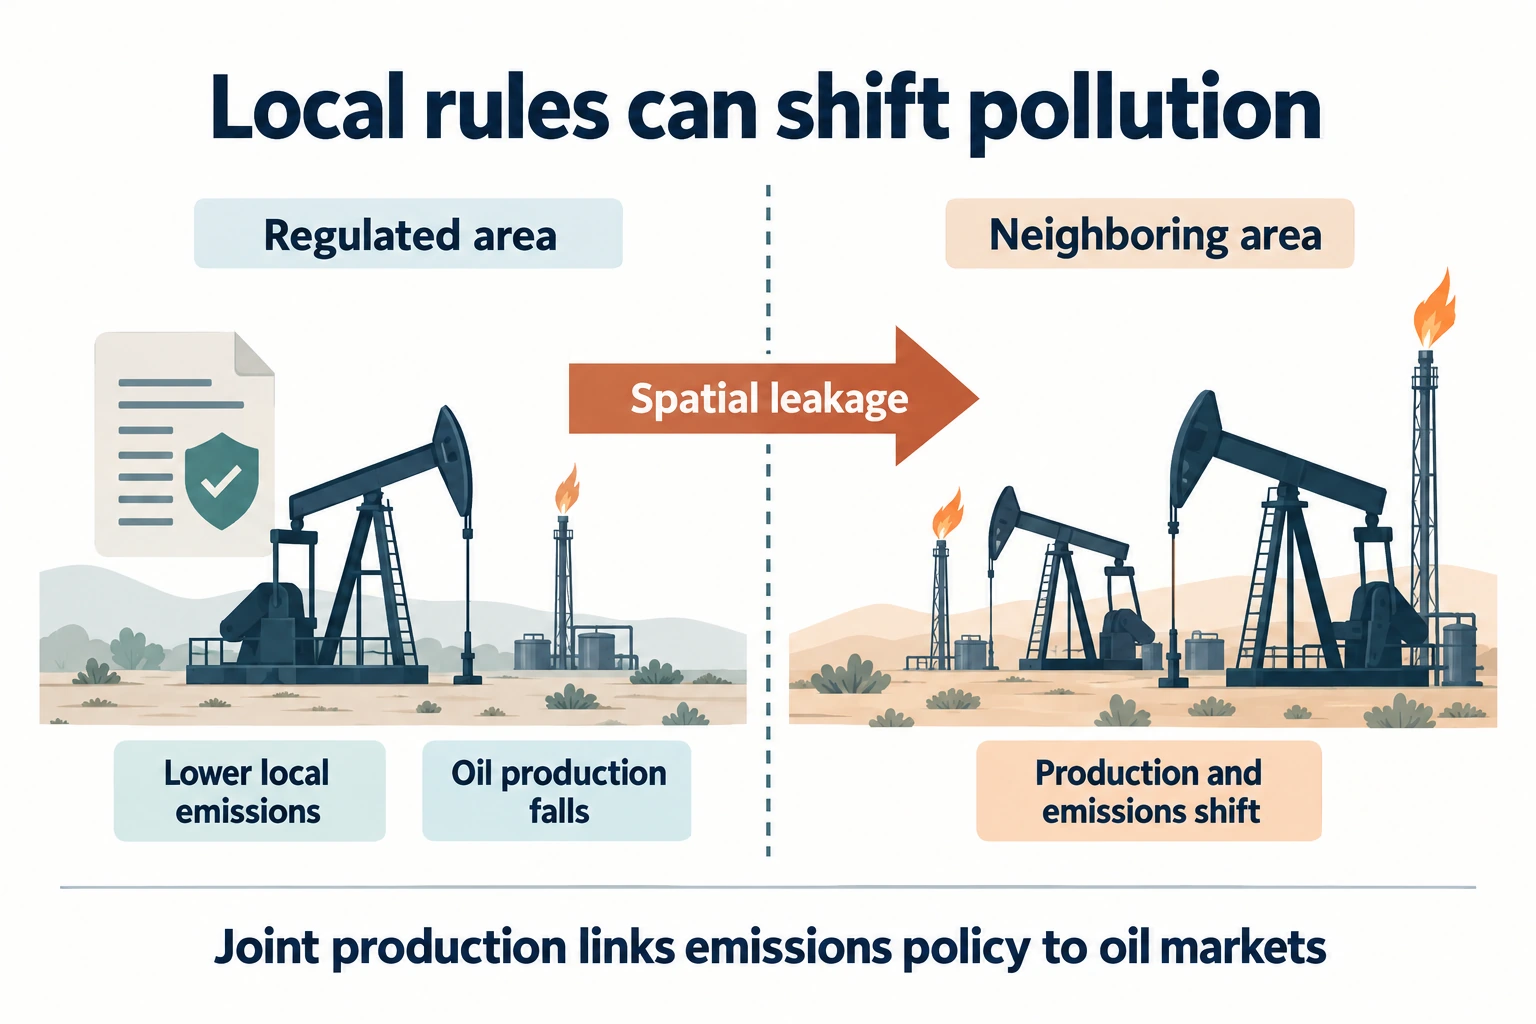
Many commercial processes yield a lower-value co-product alongside a high-value main product. Under free disposal and weak demand, co-products are frequently discharged as air, water, or land pollution. We provide the first formal treatment of co-product pollution regulation, showing that regulating the co-product is equivalent to taxing the main product. We corroborate the theory using data and a policy change from Canada’s oil sector, where excess co-produced natural gas is flared. Flaring regulation caused a 55% reduction in oil production and substantial leakage. Our results suggest regulating the $54 billion worth of gas flared globally could have significant unintended consequences.
Oil extraction jointly produces associated gas; weak demand for that co-product can make flaring privately optimal.The joint-production framework predicts more flaring when oil prices rise and less flaring when gas prices rise.Local emissions restrictions can reduce oil production in the regulated area while shifting production and emissions to neighboring areas.
Economists have established that trading in cap and trade allows the firm that values the permit the most to obtain it,
suggesting the increase in profitability or reduction in costs of the industry, compared to non-tradable permits.
Why? I propose a new perspective as a mechanism why cap and trade may increase cost efficiency of firms,
especially when trading leads to consolidation such as the case of tradable fishing permits. I show trading
helps firms improve productivity and exploit their existing economies of scale. Overcoming the unobserved-cost
challenge, I extend the literature on production functions to show a sufficient statistic to estimate
vessel-by-year economies of scale. I combine the estimate with a difference-in-difference strategy that
exploits the policy transition from non-tradable permits to tradable permits in the Norwegian cod fishery
to identify the causal impacts of trading fishing quotas. I find that vessels acquired quotas, realized
economies of scale, and moved toward the minimum average cost levels by increasing their sizes and going
fishing more often. In decomposition of the value of trading, economies of scale played a main role in the
first few years after a big vessel acquired quotas. These results highlight: (i) trade-induced consolidation
in environmental regulations can benefit firms through reducing production costs, (ii) resource rent
may be under-estimated if we ignore economies of scale, and (iii) economies of scale can be measured as
a benefit of consolidation to weigh against the market power concern.
The value of trading, part 1: vessels with the same quota can have different average costs.The value of trading, part 2: quota trading changes the allocation of fishing activity.The value of trading, part 3: economies of scale and productivity contribute to cost savings.
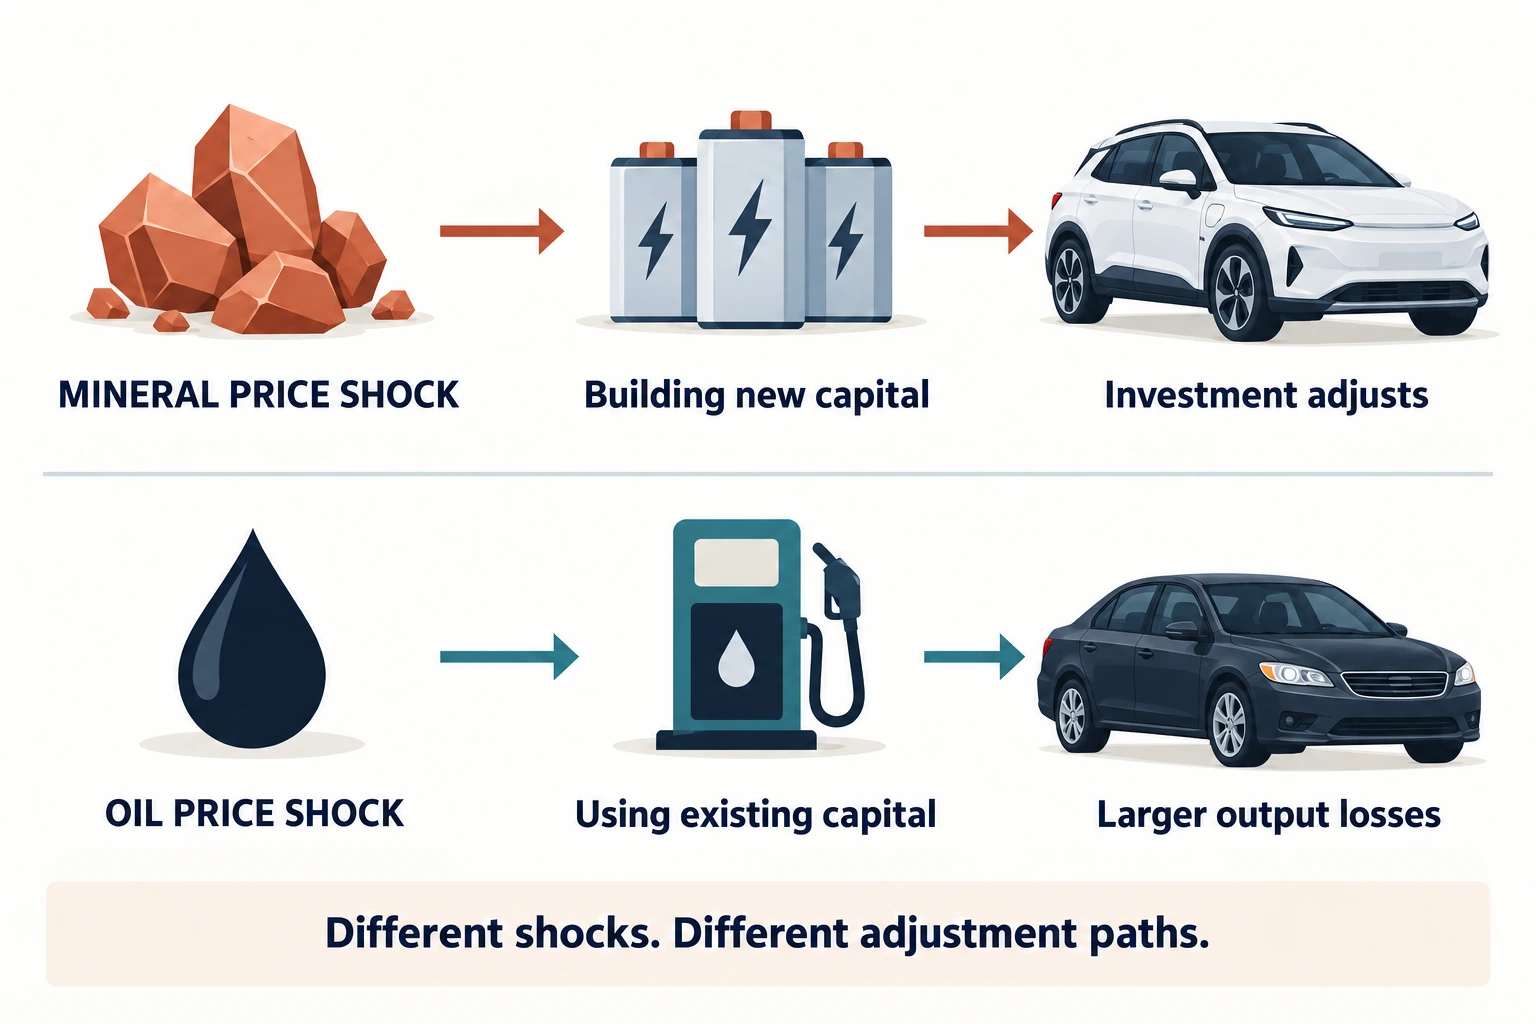
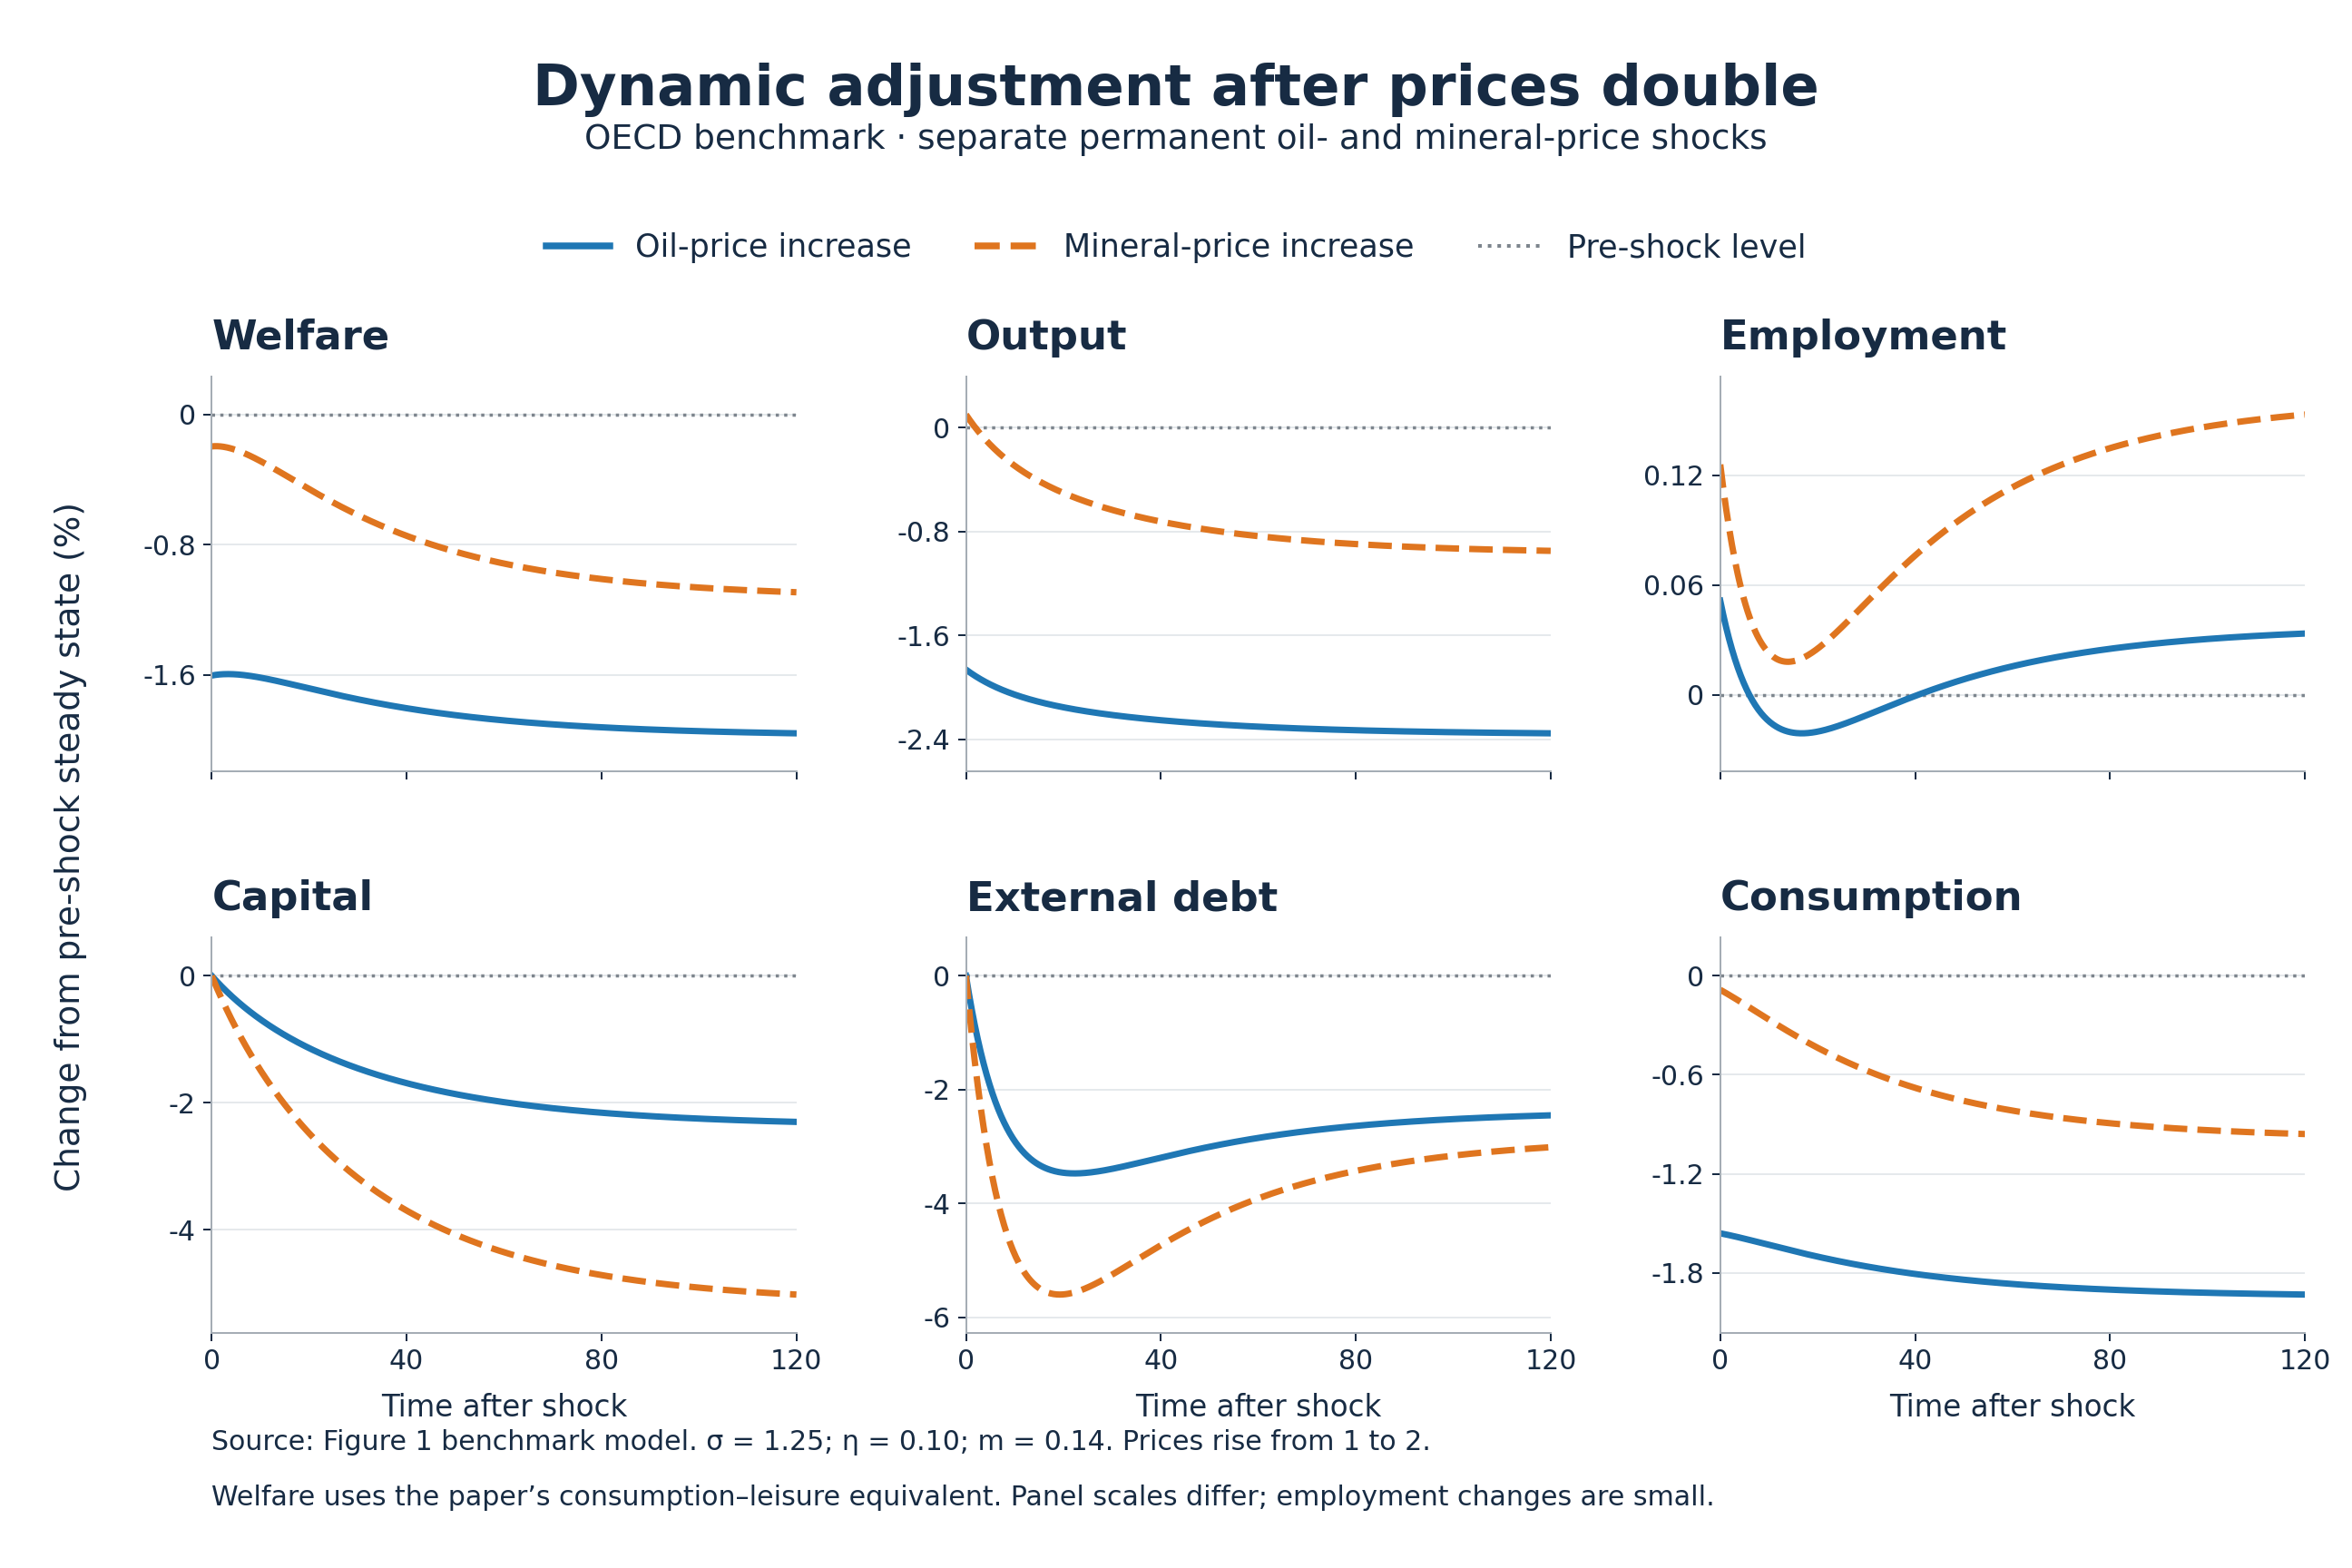
This paper compares the impacts of critical mineral prices and oil prices on an economy in a unified neoclassical growth model. Unlike oil price shocks, which affect the cost of utilizing existing capital (e.g., cars), critical mineral price shocks influence the cost of creating new capital (e.g., electric vehicles) without altering the cost of existing capital. We find that both types of shocks ultimately reduce output and welfare. However, oil-price increases are systematically more contractionary for the economy. Mineral-price increases generate comparatively larger adjustments in investment, capital, and external borrowing but smaller and more gradual losses in output and welfare, and, in capital-rich economies, can slightly raise long-run employment. These results imply that oil-price shocks remain the more serious threat to aggregate activity and welfare, whereas mineral-price shocks call for policies that smooth investment and external-balance-sheet adjustment (e.g., macroprudential tools and precautionary reserves or fiscal buffers).
Mineral-price shocks affect the creation of new capital; oil-price shocks affect the use of existing capital.Benchmark dynamic responses of welfare, output, employment, capital, external debt, and consumption to separate permanent price doublings. OECD calibration; changes from the pre-shock steady state (%).
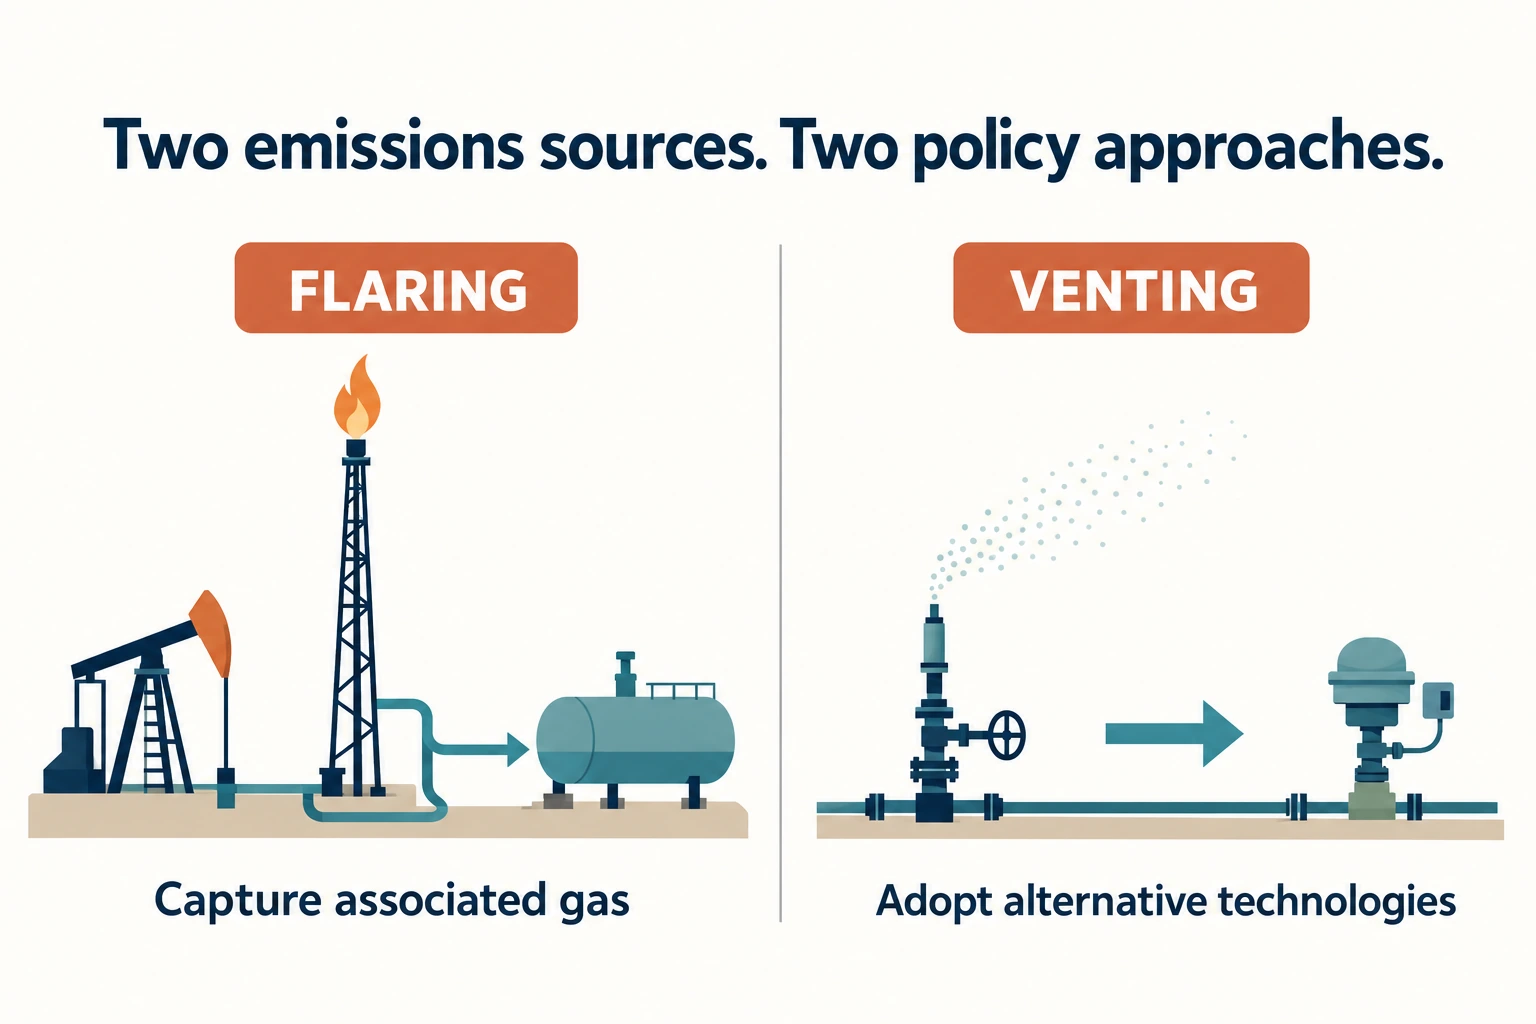
Regulating methane from the upstream oil and gas sector is seen as a low-cost method to reduce emissions. Yet, there is surprisingly little work studying the economic dynamics of flaring and venting, key sources of these emissions. We analyze data from Alberta, Canada, a jurisdiction that has regulated flaring and venting for more than two decades. We present five lessons for policy-makers. Paramount among these is that flaring and venting are each subject to different regulatory challenges, and thus require distinct regulatory approaches. The key to mitigating flaring is to encourage crude oil extractors to capture associated gases. The key to mitigating venting is to promote the development and adoption of alternative technologies for gas producers. We further estimate the relationship between production and emissions at crude oil batteries, finding elasticities of emissions with respect to production of 0.09 and 0.69 for oil and gas, respectively. While our evidence shows that both flaring and venting can be effectively controlled, regulation may also affect production and result in leakage across release-types and regions. These results inform policy-makers as they create rules to control emissions from upstream oil and gas.
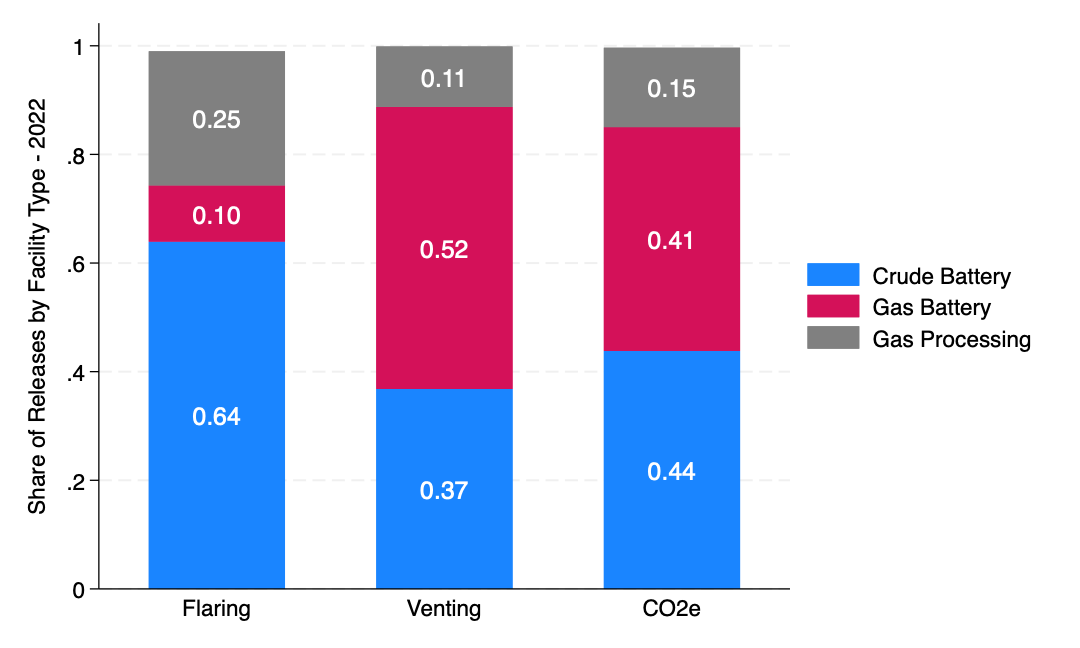
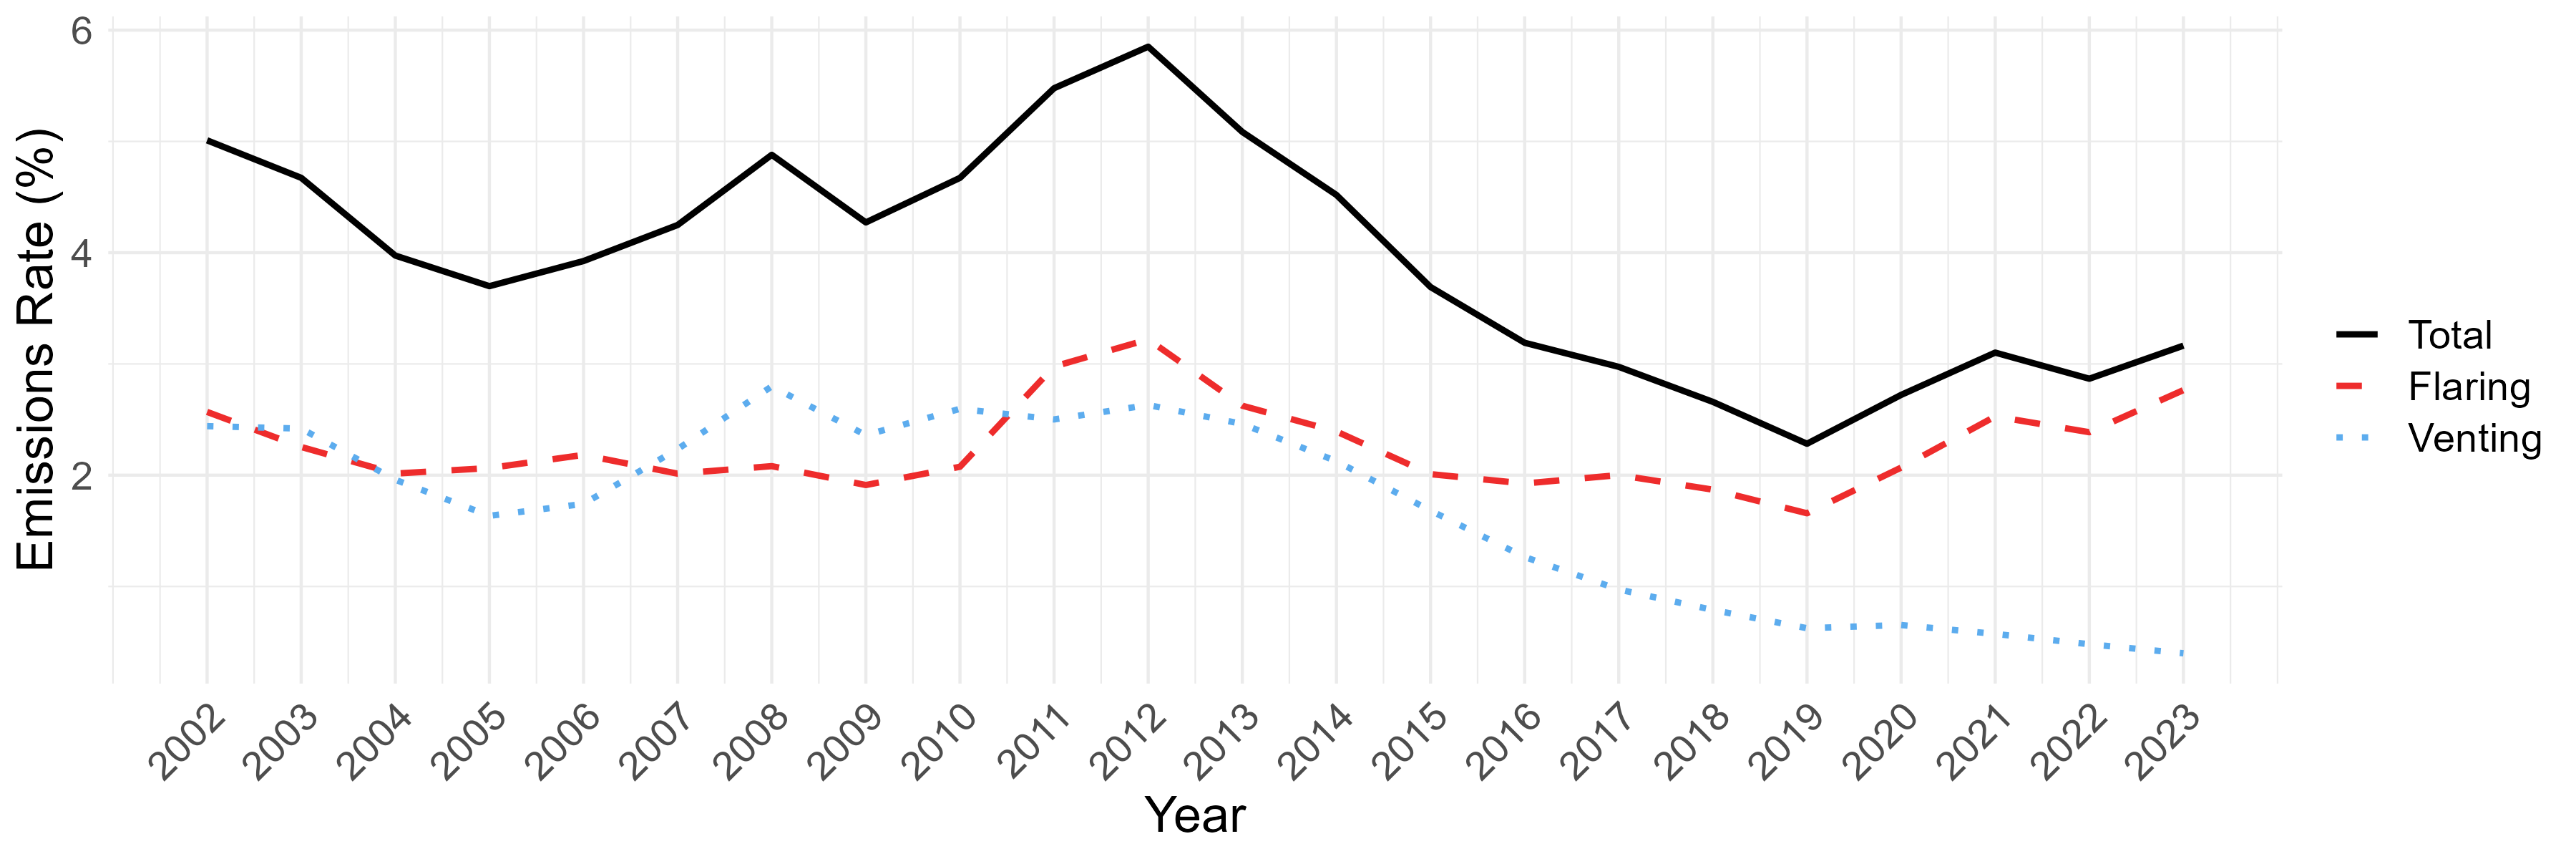
Flaring and venting call for different policy approaches: gas capture and alternative technologies.Shares of flaring, venting, and CO2-equivalent releases by facility type in 2022.Flaring and venting rates in the Alberta data.
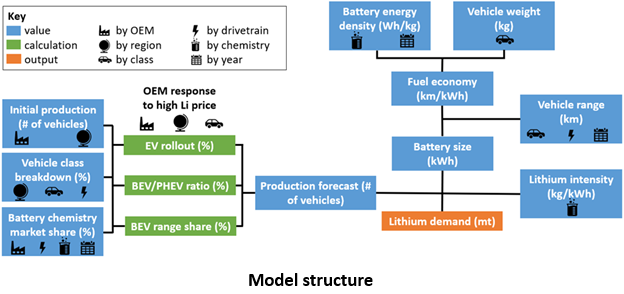
Vehicle electrification is transforming global transportation, driving unprecedented demand for critical minerals like lithium.
Ensuring a smooth transition to electric vehicles (EVs) requires a deep understanding of how automaker strategies influence lithium demand and
price elasticity over time. This research, informed by semi-structured interviews with major automakers, integrates technical insights on
current and emerging battery chemistries into a bottom-up demand model to forecast lithium demand and its price elasticity. We provide an
industry-wide assessment of both short- and long-run elasticities by analyzing automaker electrification strategies, regional market
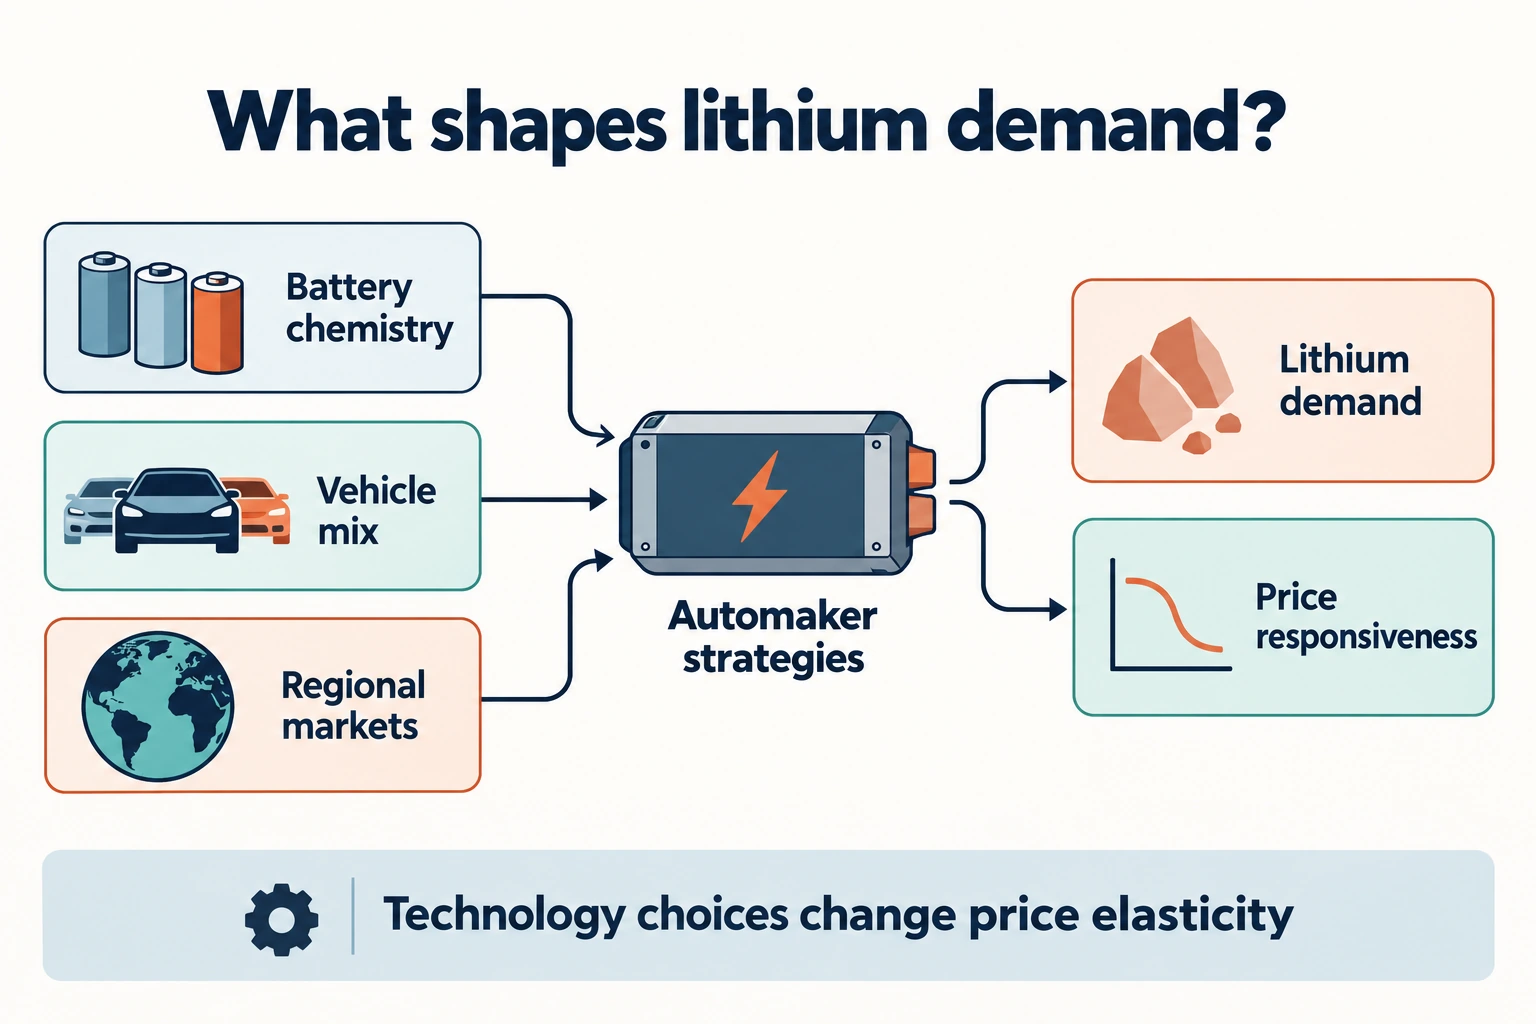
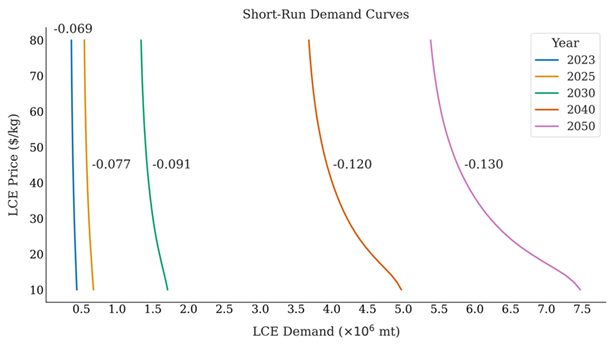
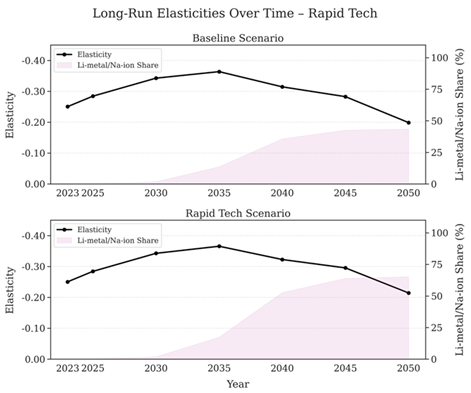
segmentation, vehicle class composition, and mixes of existing and emerging battery chemistries. We find that short-run lithium price
elasticity increases with greater optionality in EV technology, while long-run elasticity initially rises before declining as the market
matures. These insights offer valuable guidance for industry and policymakers seeking to design electrification strategies
that mitigate risks associated with lithium price volatility.
Battery chemistry, vehicle mix, and regional markets shape lithium demand and price responsiveness.The bottom-up lithium-demand model used in the article.Projected short-run lithium demand curves and their price elasticities.Long-run lithium price elasticities under the modeled scenarios.
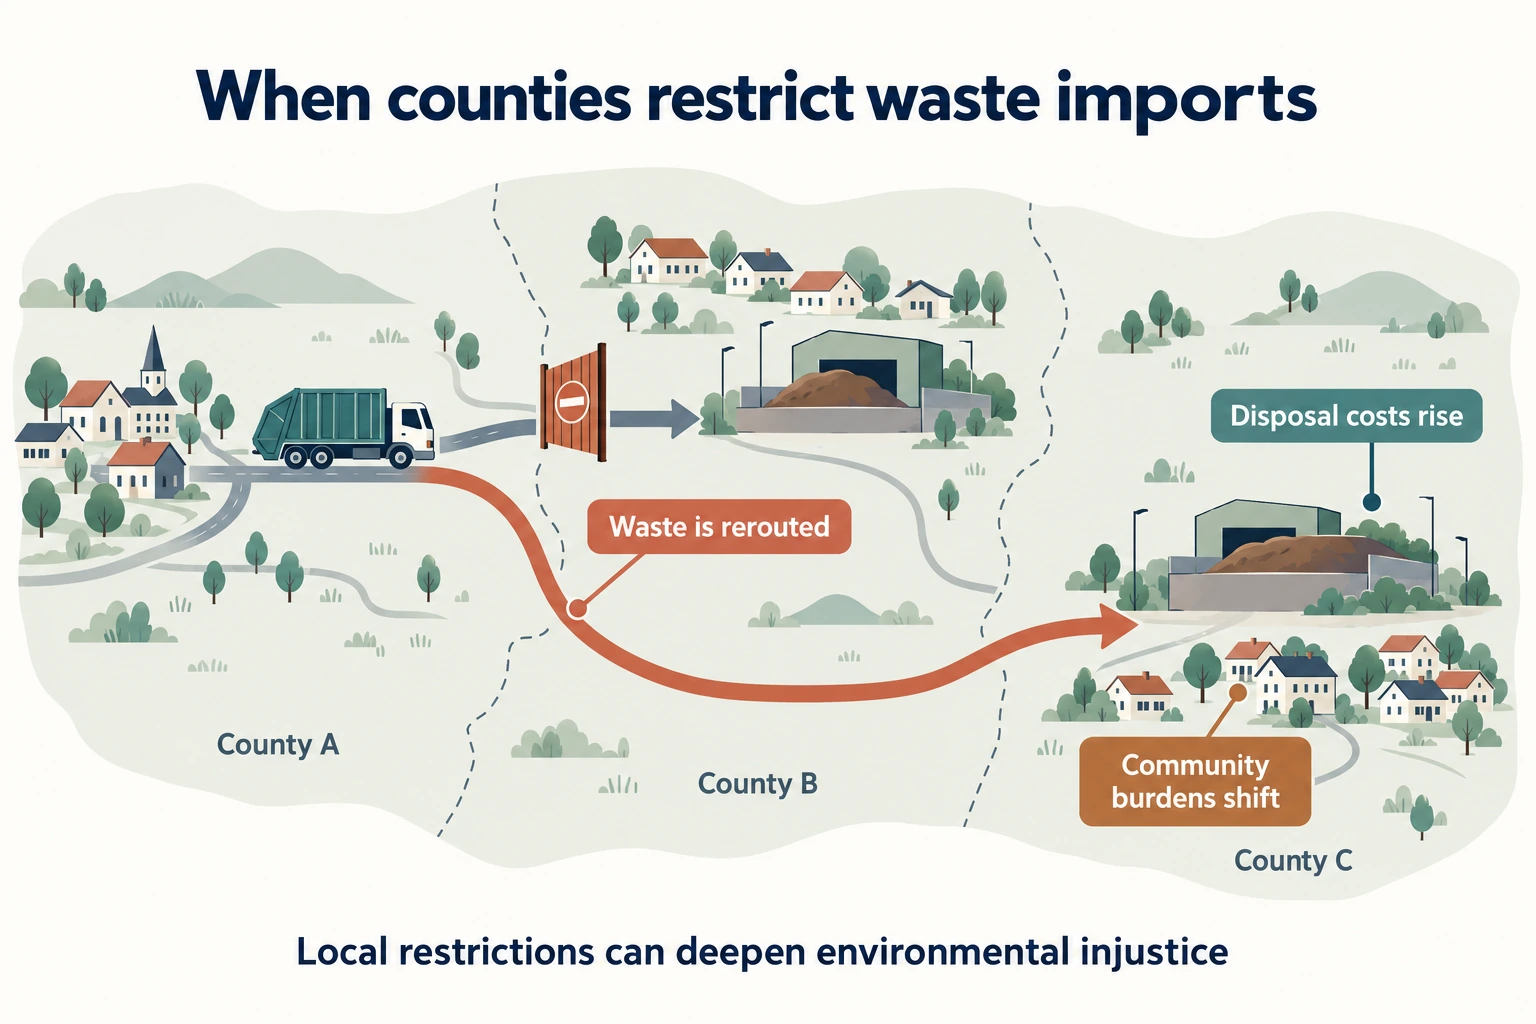
Many recent US Congresses have proposed bills that allow state and local governments to
restrict interjurisdictional waste shipments. Using data on intercounty waste flows in California
and a random utility model of haulers’ decisions about where to deposit waste from each
county, this paper studies the economic costs of import bans and import taxes and the
implications on the distribution of waste disposal by race (and ethnicity). I find NIMBY-motivated
laws would reduce intercounty waste transport at substantial economic costs. Furthermore, a
NIMBY law enacted in a county, despite reducing the county’s imports, could increase total
intercounty waste in the whole state, generating additional external costs of transportation. A
universal import ban in all counties would reduce transboundary waste but it would lead to
substitution of waste away from facilities near white residents and toward facilities near
Hispanic residents, exacerbating distributional concerns.
Restrictions on waste imports can reroute disposal, increase costs, and shift burdens across communities.
Recent empirical analyses show consumers in electricity and water markets respond to average price rather than marginal price,
calling for information provision policies that help correct the consumers' bias.
This paper characterizes the regulated tariff if the regulator is informed about the average-price
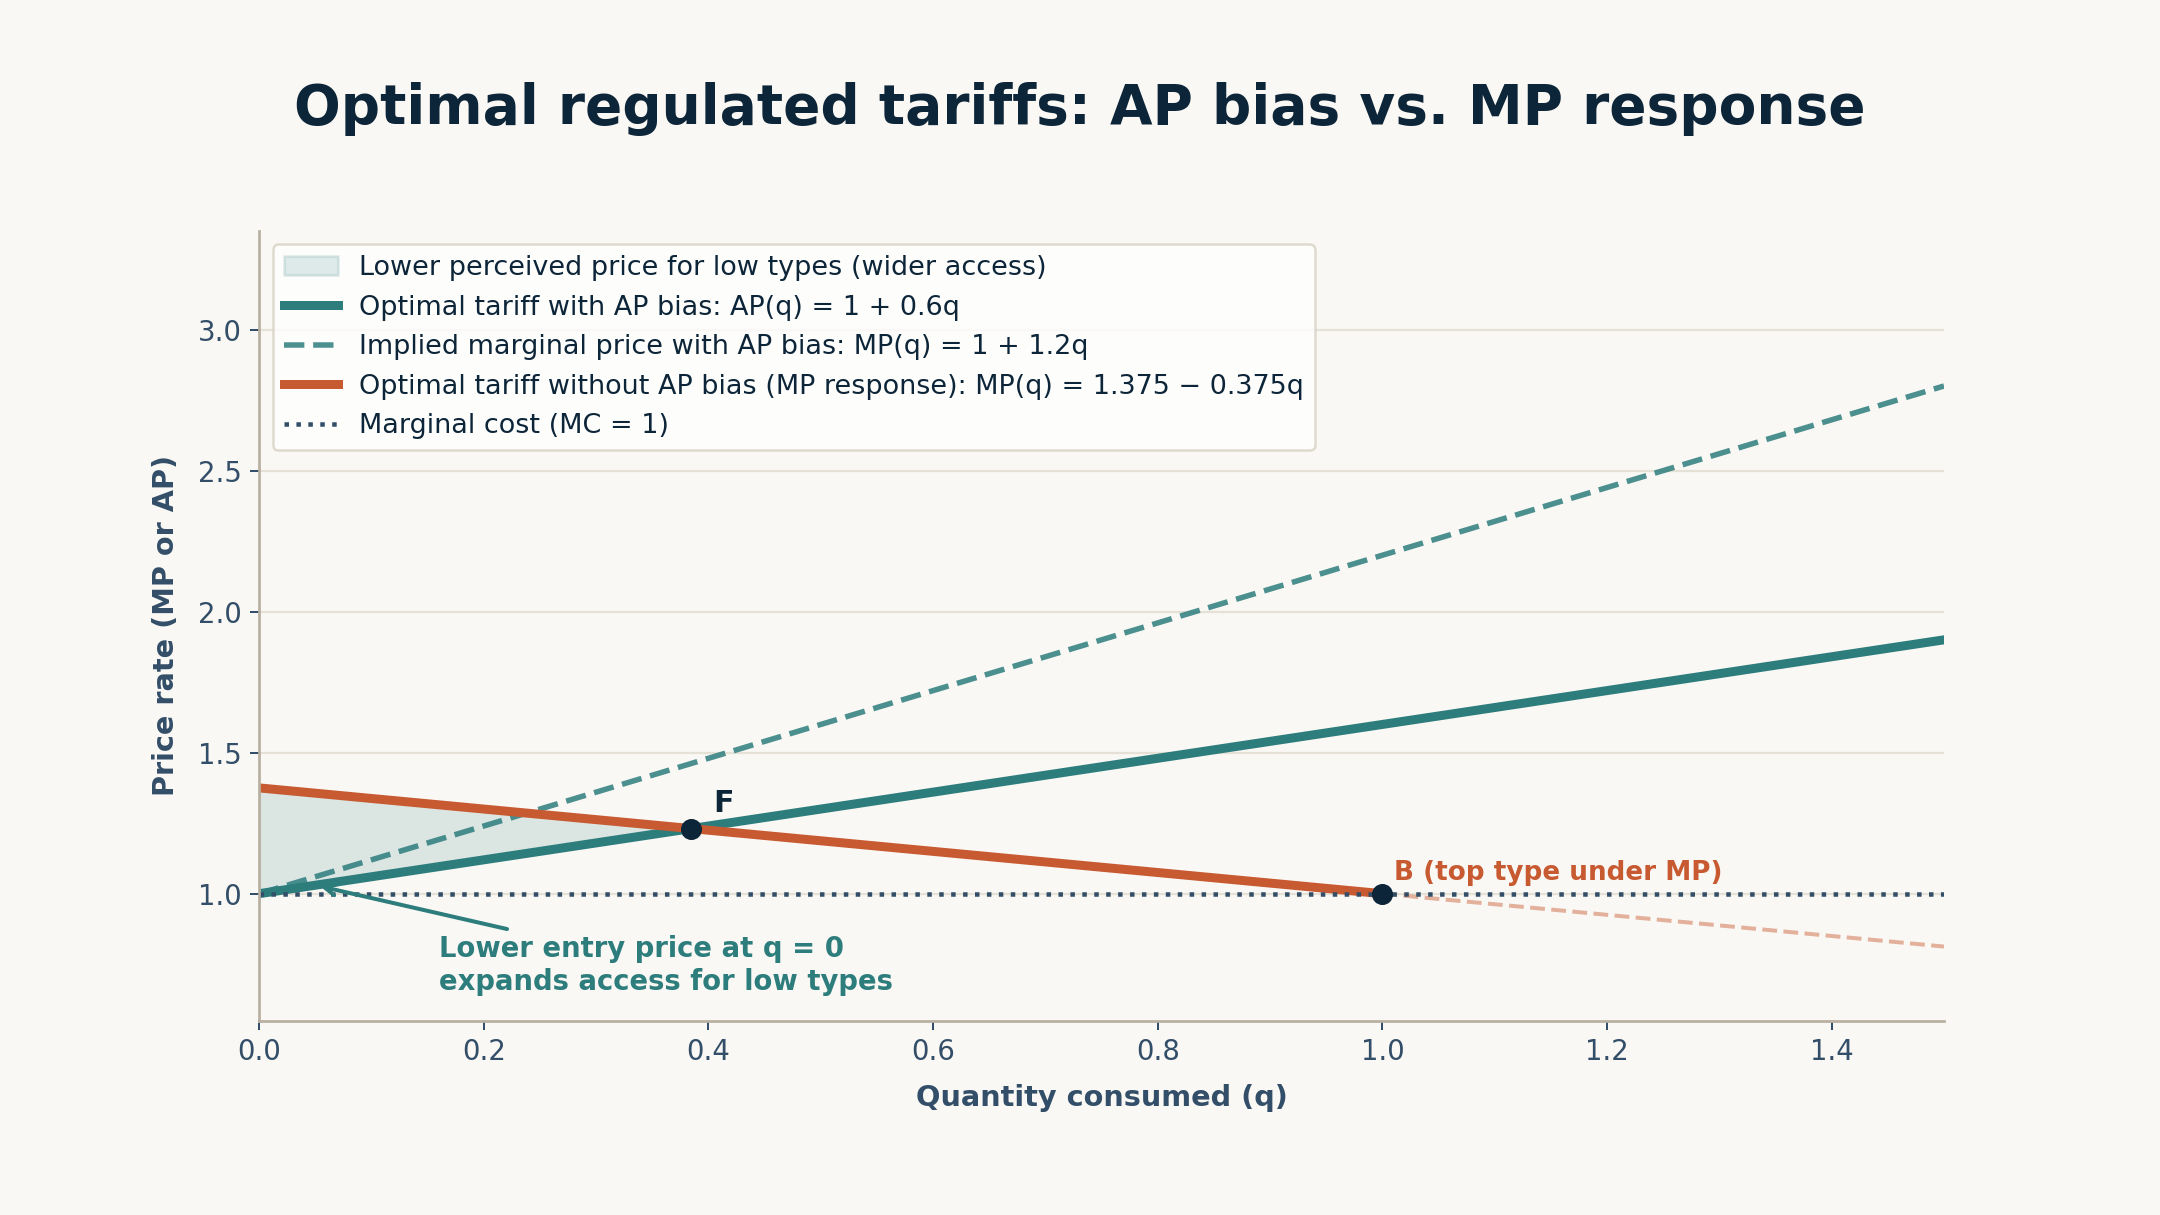
response of consumers. I find the regulated tariff for biased consumers promotes equity gains
by featuring quantity premia and providing access to utility consumption for a larger population
than in the world of rational consumers. The world of biased consumers may also yield higher total
welfare. These results bring up the opportunity costs of the information provision programs that help consumers correct the bias.
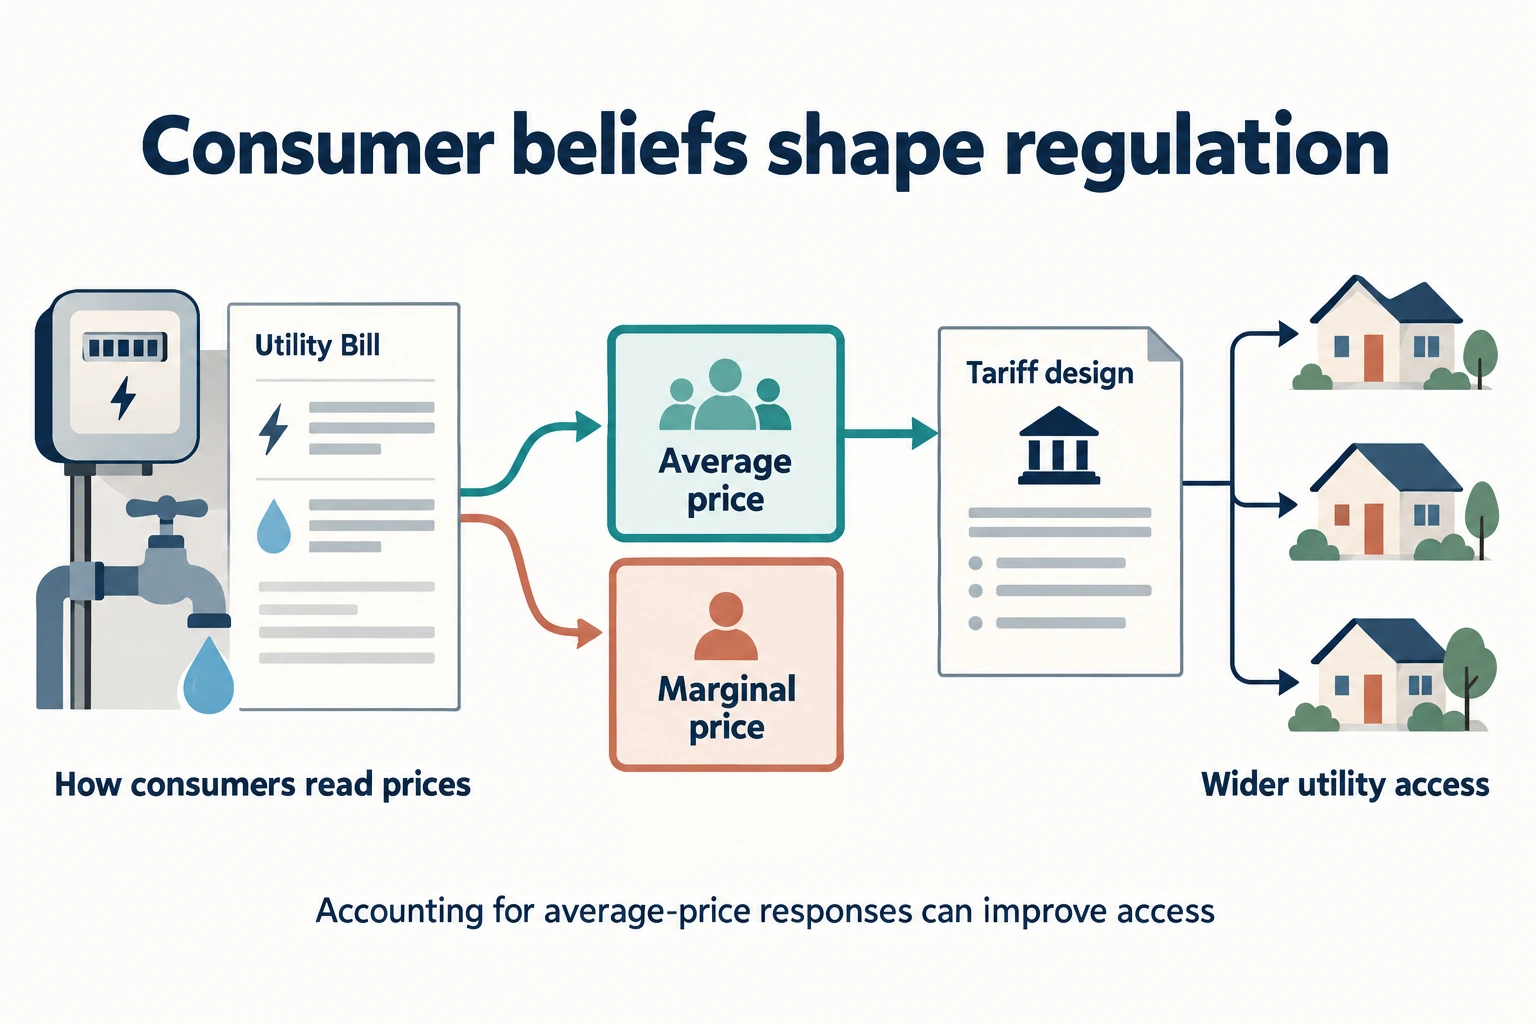
Accounting for average-price responses can change regulated tariffs and expand access to utilities.Optimal tariff schedule under average-price bias features quantity premia and wider participation than the rational benchmark.
We model a spectrum auction where firms purchase units to participate
in a constrained, multi-product, downstream market.
We use dynamic programming techniques to numerically solve for the
optimal bidding strategy in a clock auction. Firms value constraining
competitor market power, so incumbents often bid aggressively to shut
out entrants. We find that high cost firms may hold up the market,
so the auction may be inefficient and generate zero revenue.
An auction may be optimal for a regulator maximising total surplus.
A regulator maximising auction revenue sets reserve prices high enough
to restrict spectra sold, effectively behaving as a monopolist.
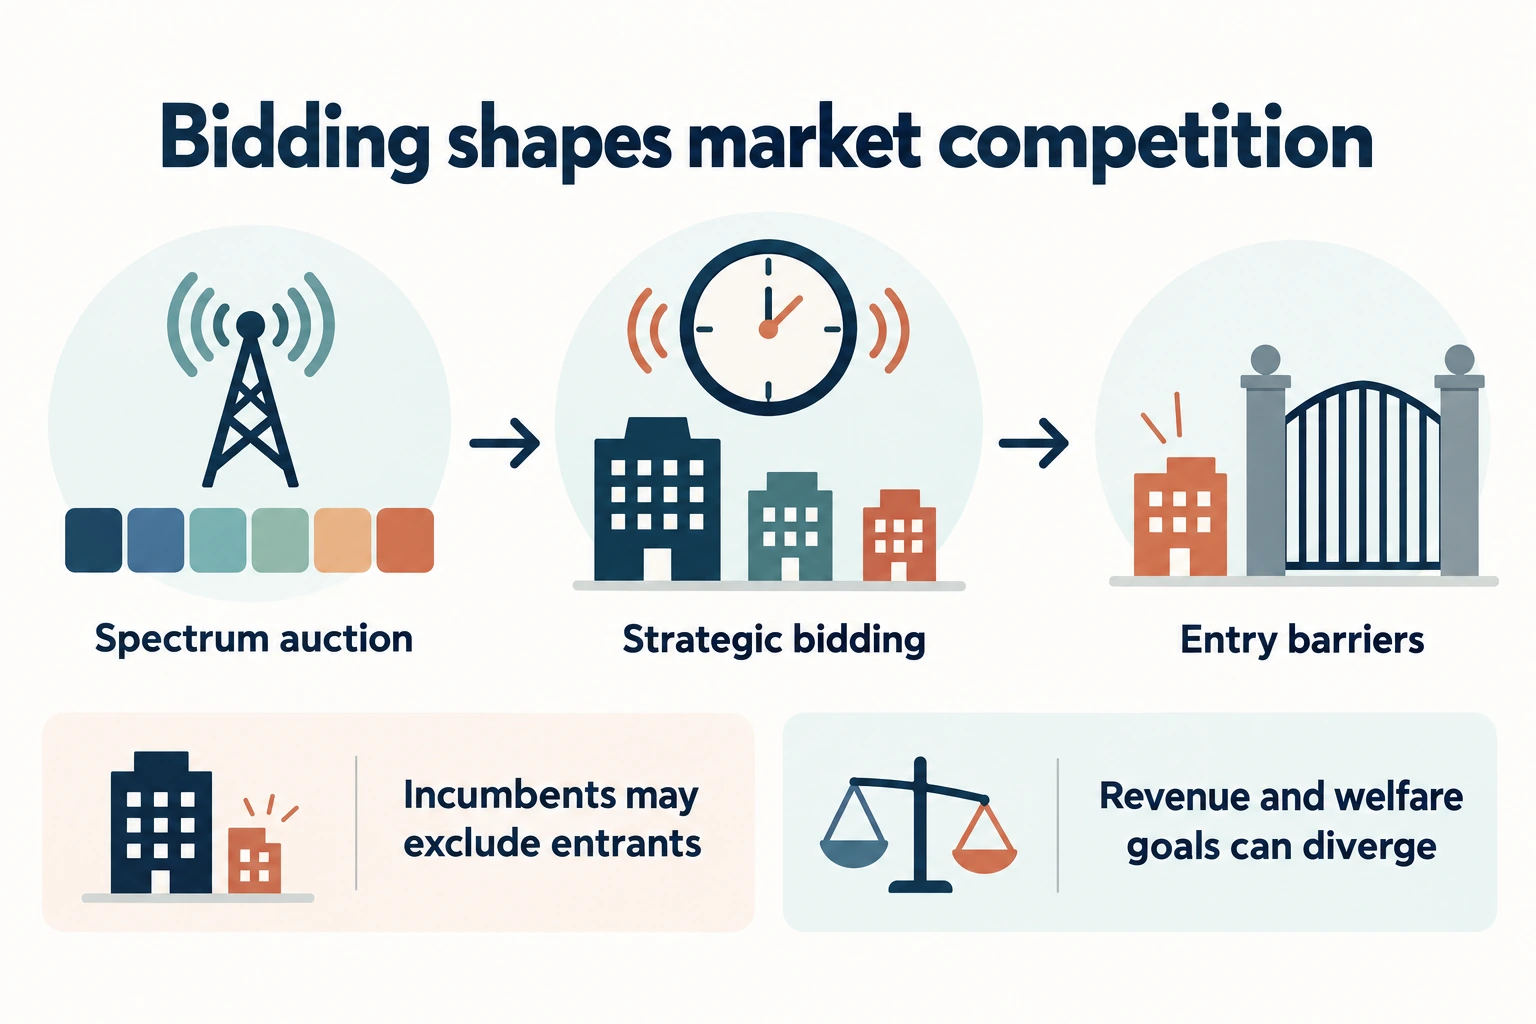
Strategic bidding can affect entry, efficiency, and the trade-off between auction revenue and welfare.
[2] Is the ‘Digital Dividend’ Spectrum Overpriced?, Competition & Regulation Times, New Zealand Institute for the Study of Competition and Regulation, 2013, with Toby Daglish and Yiğit Sağlam.
[1] Divvying Up the ‘Digital Dividend’, Competition & Regulation Times, New Zealand Institute for the Study of Competition and Regulation, 2012, with Yiğit Sağlam and Toby Daglish.
RESTING PAPERS
Living near Trash: Testing Residential Mobility in the Context of Solid Waste Disposal
[Latest Version (2019)]
Chapter 3 in my PhD dissertation
Abstract
Forming sound environmental justice policy involves understanding whether the correlation between race
and environmental bads results from the disproportionate siting of locally unwanted land
uses or nuisance-driven residential mobility. This paper presents evidence of residential sorting
in the context of municipal solid waste disposal facilities, using a difference-in-difference
strategy. Specifically, I compare changes in population after an opening (and closing) of a
trash site between blocks within one mile to faraway blocks. Results show a 11%
decrease in white population and a 44% increase in Hispanic population in a block
after a trash site opened within one mile. Closing the site does not change white
population immediately while inducing a 11% fall in Hispanic population, relative
to the period during which the site was operating.
The Spatial Term Structure of Spot Freight Rates with Roar Adland and Vit Prochazka
Abstract
Spot market indices for the freight markets in bulk shipping, such as those produced by the
Baltic Exchange, are estimated by brokers based on a fixed lead time (e.g. “Laydays/cancelling
10/20 days from index date"). In reality, ships can be fixed anywhere along a route such that
there may also be a spatial component in the spot freight rate for individual fixtures.
Consequently, there is not a single spot rate on a given date, but many along the distance (or
time-to-loading) dimension. That is, there exists effectively a spatial “term structure of spot
freight rates". Such a spatial component may reflect the degree of risk aversion of shipowners
and charterers and is therefore expected to be market dependent. For instance, charterers may
worry about transportation shortage in a strong market and be willing to fix ships early at
relatively higher rates, while owners may accept a discount for early ships in a poor market just
to secure employment. The objective of this paper is to investigate the time-varying properties
of spot rates jointly in the time and space dimension.
REFEREE SERVICE
Review of Environmental Economics and PolicyJournal of Environmental Economics and ManagementJournal of the Association of Environmental and Resource EconomistsInternational Journal of Industrial OrganizationResource and Energy EconomicsJournal of Economics (Zeitschrift fur Nationalokonomie)Bulletin of Economic Research